Your Portfolio Tracker Is Answering a Question You Never Asked

— A portfolio balance answers "what is it worth." It cannot answer "how did it get there," because nearly every tracker stores positions and throws away the events that produced them. That gap has three expensive consequences for anyone investing across borders: there are four different numbers called "return" and trackers show one, the tax that shapes your dividends is decided by a combination of countries that no dashboard models, and there are thresholds you cross with no event firing anywher
Key Takeaways
- Your Portfolio Tracker Is Answering a Question You Never Asked.
- — A portfolio balance answers "what is it worth." It cannot answer "how did it get there," because nearly every tracker stores positions and throws away the events that produced them.
- I discovered that most portfolio trackers cannot answer that cleanly — and the problem gets worse when your broker, residence, and ETFs sit in different countries.
TL;DR: I wanted to know whether my portfolio was growing because of my investing decisions, my contributions, or simply the market. I discovered that most portfolio trackers cannot answer that cleanly — and the problem gets worse when your broker, residence, and ETFs sit in different countries. This is what I learned while trying to untangle it, and why I ended up building my own tracker. The number sat on my broker's home screen, green and precise to two decimals: roughly eighteen thousand dollars earned from investing across the whole period I had been at it. I looked at it for a long time and realized I did not know what it actually included. Did it count dividends — the reinvested ones, or only the ones that arrived as cash? Was that before or after tax withheld in a country I do not live in? Did it include positions I had already sold, or only the ones I still held? Were fees included? Was it measured from my first-ever deposit, or only from the day I opened this account and transferred assets into it? Each of those questions can move the number. Some can move it by thousands. Yet the dashboard offered one figure, in green, with no way to open it up. By then I had been investing for several years, across more than one account and more than one strategy. Some positions had been sold, some dividends reinvested, and some assets transferred between brokers. The number looked extremely precise while being surprisingly difficult to audit. I assumed the breakdown was hidden behind an advanced tab I had not found yet. It was not. Nobody was keeping that history in a way that answered the questions I actually had — not my broker, not my spreadsheet, and not any of the tools I tried. The Category Assumption I am a self-taught engineer, twenty-four years old, and I have been accumulating capital for years with financial independence as a concrete goal rather than a vague aspiration. My strategy is unfashionably boring: broad market exposure, a monthly transfer that leaves before I can think about it, reinvest everything, and avoid unnecessary trading. It worked. The portfolio reached six figures through contributions and time, not because one trade happened to go right. Then my income changed and my contributions became uneven. Some months were strong, some were thin, and some had gaps. That was the moment when a portfolio balance stopped being useful feedback. The balance could still go up, but "it went up" now had several completely different meanings: I contributed a lot and the market was flat. I contributed almost nothing and the market carried the portfolio. I contributed steadily and both worked. I contributed nothing, the market fell, and dividends plus a favorable exchange rate papered over the decline. Those are not four versions of the same outcome. They imply very different things about whether my plan is working. The question I actually needed answered was simple: am I still on track while contributing less than I used to? A balance cannot answer that. It mixes my behavior and the market's behavior into one number and refuses to separate them. Every tool I tried seemed to share the same underlying model: A portfolio is a set of positions with prices. Inside that model, a deposit is just a bookkeeping event that makes the pie bigger. The history of how the portfolio got there is not really treated as first-class data. It is mostly a side effect that gets overwritten every time prices move. That model also discards the part I most wanted to learn from. My portfolio did not always look the way it does today. I spent a few years pursuing dividend income toward a $500-per-month target. Later, I came around to the view that, during accumulation, income that you immediately reinvest can become a tax event with extra steps — especially once geography enters the picture. What I eventually converged on was much simpler: a global accumulating fund as the core, short-term treasuries, and gold. Look only at my holdings today and you might conclude I had always been a three-fund accumulator. That would be false. A holdings screen is a snapshot of the conclusion. I wanted the working, including the parts I got wrong. Four Things Are Called "Return" — and They Are Not the Same Thing This is where a preference became an actual problem. I calculated my return one way. Then I calculated it another way and got a different answer — not slightly different, but opposite in sign. The cleanest illustration looks like this: Date Event Portfolio value 1 Jan Deposit $1,000 $1,000 1 Jul Holdings rise 50% $1,500 1 Jul Deposit $9,000 $10,500 31 Dec Holdings fall 10% $9,450 Time-weighted return Time-weighted return, or TWR, is designed to remove the effect of deposit timing. It is useful when you want to evaluate the strategy itself or compare it with an index. The two sub-periods are chained together: 1.50 × 0.90 − 1 = +35% That is an excellent year for the strategy. Money-weighted return Money-weighted return, commonly calculated using XIRR, asks a different question: what did the investor's actual money earn, given the timing of every cash flow? In this example, the result is about −9.7%. The investor put in $10,000 and ended the year with $9,450. Both numbers are correct. The strategy had a great year. The investor lost $550 because 90% of the money only arrived for the bad half. I do not think a dashboard that shows only one of these and labels it "your return" is necessarily dishonest. It is compression, and from a product-design perspective it is understandable. One percentage is easier to render than two percentages and an explanation. But the compression is exactly where the information I wanted disappears. Once I started pulling the concept apart, the word "return" turned into several distinct quantities: Unrealized gain — the revaluation of what I still hold relative to what I paid. It says nothing about positions already sold and nothing about income. Realized gain — the gain or loss locked in by closing positions. Real, spendable, and often taxable somewhere. Personal return (XIRR) — the annualized rate my actual money earned, with each deposit weighted by how long it was invested. Portfolio return (TWR) — the performance of the investment strategy with external cash flows removed, which makes it more comparable with an index. For someone contributing unevenly, the gap between XIRR and TWR is not noise. It can be the finding. If they diverge sharply, the timing of my contributions — not my fund selection — may have dominated the year. That is actionable in a way neither number is on its own. And it reframes the original $18,000 figure. Before that number means anything, it needs to be split into at least: contributions made, market movement, gains realized, income received, fees paid, and tax withheld. Presented as one number, it is not really an explanation of performance. It is a summary without the evidence. The Layer That Lives in a Browser Tab Instead of Your Portfolio The second half of the problem is geography, and it makes all of the above harder. I live in South Africa. I run my business through Georgia. My brokers are elsewhere again, and the funds I own are registered in countries I have never set foot in. None of this was planned as an elaborate international structure. It happened gradually: I moved countries, my work became remote, the brokerage account stayed where it was, and the funds themselves were domiciled somewhere else again. At some point I realized that four different jurisdictions were touching the same portfolio while every dashboard still presented it as if it were just a list of tickers. That is increasingly normal for people whose work no longer requires a specific building. My financial life sits across several layers that have no obligation to agree with each other: where I live, where my business is registered, where my broker is based, and where each fund is domiciled. I started where most people start: a fund is a fund. Pick the index, buy the cheapest vehicle tracking it, and move on. Inside a single country, that can be perfectly reasonable advice. Cross-border investing breaks the simplicity. The first crack: not every fund is available everywhere Some of the largest and cheapest US ETFs are not practically accessible to ordinary retail investors through some European brokers because of local product-documentation rules. That is one reason international portfolios often end up using UCITS versions of familiar indices rather than the US-listed products themselves. What looks like an investment preference may actually be a jurisdictional constraint. The second crack: the dividend that arrived smaller than expected The next surprise was a dividend that arrived visibly smaller than I had modeled. It was not a brokerage fee. It was not a bad quarter. It had been taxed before it reached me, by a country I do not live in, at a rate I did not know applied to me. A foreign dividend can pass through more than one tax layer. At source, the country connected to the security may withhold tax before the money reaches the investor. For a non-US investor receiving US-source dividends through a US-domiciled fund, the statutory US withholding rate is generally 30%, often reduced by treaty where one applies and the required documentation is valid. Then the investor's country of residence may tax the same income again under its own rules, sometimes allowing a credit and sometimes not. The important point is that these steps are independent. Moving somewhere with no local dividend tax does not automatically make source-country withholding disappear. That can leave internationally mobile investors with a recurring drag they never see on the portfolio overview screen. On an illustrative portfolio producing $571 per year in dividends from US-domiciled funds, the source-country result can differ by residence: United Arab Emirates: no US income-tax treaty rate on ordinary portfolio dividends in this example, so 30% withholding means roughly $171 withheld and about $400 reaching the investor. Portugal: assuming a 15% treaty rate, roughly $86 is withheld and about $485 reaches the investor. Germany: assuming a 15% treaty rate, roughly $86 is withheld and about $485 reaches the investor. Same funds. Same dividend amount. Same dates. Different residence, different cash result before anyone has picked a single stock differently. That also changed the way I thought about dividend investing. A strategy built around receiving cash that I intend to reinvest immediately can also be a strategy built around repeatedly triggering withholding along the way. That may be perfectly reasonable for someone living on the income. For someone still accumulating, it deserves a closer look. Why Irish-Domiciled UCITS Funds Can Change the Equation There is an interesting structural wrinkle. An Irish-domiciled UCITS fund holding US stocks can generally suffer 15% US withholding at the fund level under the US-Ireland treaty. Ireland generally does not impose another layer of withholding on distributions from Irish funds to many non-resident investors. That means an investor living in a country without a US tax treaty can sometimes receive US equity exposure through an Irish fund with a lower source-country withholding drag than if they held a US-domiciled fund directly. The obvious conclusion is tempting: Everyone outside the US should just hold Irish UCITS funds. I believed that for about a week. Then I ran the numbers position by position and watched the conclusion fall apart. One switch improved the annual result by roughly $32. Another made it worse by about $7. Why? Because the comparison uses two different denominators. The tax saving scales with dividend yield. The expense-ratio penalty scales with the entire position value. A low-yielding fund may have very little withholding to save, while a more expensive UCITS alternative charges its higher expense ratio against the whole balance. So the answer depends on the specific fund, the investor's residence, the position size, the fund's dividend yield, the treaty path, and the cost of the alternative. Lower withholding does not automatically mean a better outcome. It means one term in the equation improved. The Threshold With No Event The most unsettling discovery had nothing to do with annual returns. A non-US person's estate can face US estate-tax exposure on certain US-situs assets. US-domiciled ETFs and individual shares of US corporations can fall into that category. For nonresident, non-US citizens, the filing threshold can be as low as $60,000 of US-situated assets, subject to treaty rules and individual circumstances. Estate-tax rates can reach 40% at the top end. This is not income tax. It is estate tax. Whether it actually applies, and how much is ultimately due, depends on treaty coverage, deductions, ownership structure, and the circumstances of the estate. The key point for a long-term investor is simpler: it is a threshold you can cross without any visible event happening in your portfolio. No trade occurs. No email arrives. No warning appears on the broker dashboard. From the dashboard's point of view, nothing happened. A long-term index investor can cross that line in an ordinary month of an ordinary year simply because the portfolio grew. I had crossed it long before I knew it existed. Moving Countries Changes the Portfolio Without Moving a Single Share None of this is static because people move. When residence changes, the portfolio itself may not move at all. Not one share needs to change hands. But the surrounding rules can change anyway: the withholding rate on future dividends, local taxation of income and gains, treatment of accumulating funds, reporting requirements, what products remain practical or available to buy, and whether the existing structure is still tax-efficient. So the honest answer to "how much did tax cost this portfolio?" is not always one rate applied across history. It can be the rate that applied at the time, changing partway through, applied only to the relevant income in each period. Currency creates a smaller version of the same problem. If a tracker converts a contribution made three years ago using today's exchange rate, the investor's historical contribution record silently changes every time the currency moves. That is conceptually wrong. Cash flows belong at the exchange rate on the date they occurred. Only what is held today belongs at today's rate. It sounds pedantic until you watch your own record of what you contributed change while you are not touching the account. What I Built Eventually I stopped trying to force the questions I cared about into tools that were built around a different model. So I built BorderFolio around a different assumption: The history matters as much as the holdings. Instead of starting with today's positions, it starts with the events that created them — contributions, purchases, sales, dividends, fees, and withholding. Statements can be imported from PDF or CSV, entered manually, or reconstructed from screenshots when needed. I deliberately chose statement imports instead of requiring permanent broker credentials because I did not want to hold anyone's brokerage login, including my own. From those confirmed transactions, the system can build a history rather than just a snapshot. The goal is to separate: what I contributed, what the market added or removed, income received, fees and withholding, realized gains, unrealized gains, personal return, and portfolio return. Contributions are kept as first-class records, with dates, streaks, gaps, and pace against plan. Personal return and portfolio return sit next to each other instead of one being chosen and labeled simply "return." Monthly snapshots preserve what the portfolio looked like at the time, so history does not get silently rewritten every time today's prices move. And the cross-border layer sits next to the portfolio instead of living in a separate browser tab: fund domicile, configured residence, withholding assumptions, and structural comparisons between different fund choices. One comparison I care about is showing both sides of a potential switch: the withholding that might be saved, and the expense ratio that might be paid instead. That avoids presenting "lower withholding" as if it were automatically better. What It Cannot Do I think financial software should be explicit about the places where the answer is incomplete. BorderFolio is built on statement imports rather than live broker APIs. That means the investor has to upload something periodically, usually once a month if they want a clean history. Every calculation is only as good as the records imported. A missing statement creates a hole. The tool shows that hole rather than pretending it can infer data that was never recorded. Time-weighted return also needs valuations around external cash flows. If a valuation is missing, an approximation may be required. When that happens, it is labeled as an approximation rather than presented with false precision. That means some portfolio-return calculations genuinely improve as more monthly history accumulates. You cannot reconstruct a valuation that nobody recorded. The cross-border figures are also informational estimates based on published treaty rates, fund domicile, and available fund documentation. They cannot know every detail of a person's tax situation and they are not tax advice. And when a metric cannot be computed, the tool should say so. A number that cannot be worked out and a number that is genuinely zero must never look the same on a screen. What I Watch Now My next milestones are $200,000, then $250,000, with $1 million as the long-term destination. What I watch now is not simply the account balance. I watch: the contribution record, the split between what I put in and what the market did, the gap between my personal return and portfolio return, income and withholding, and whether the structure of the portfolio still makes sense for where I live. Some months the answer is reassuring: the contribution pace still reaches the milestone even if the market was boring. Some months it is not. Both answers are useful. Neither is visible in the green, two-decimal number on a broker's home screen. If you find a number in BorderFolio that is confidently, plausibly, quietly incorrect, I want to know about it more than I want a signup. The interesting failures in a tool like this are not crashes. They are calculations that look believable enough that nobody questions them. You can reach me at admin@borderfolio.app. BorderFolio provides informational portfolio analytics only. Nothing in this article is investment, financial, legal, or tax advice, and no figure is a recommendation to buy, sell, or hold any security. Illustrative figures are exactly that. Tax rules change and depend on individual circumstances, so anything material should be verified with a qualified adviser in the relevant jurisdiction.
Read Complete Original Article
Published originally on HackerNoon
Related News
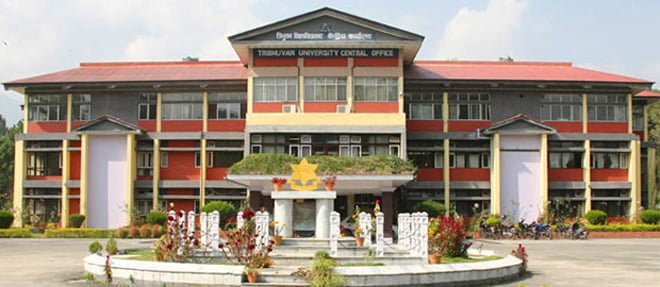
‘डिजिटल त्रिवि’देखि ‘रिसर्च युनिभर्सिटी’सम्मः के–के हुँदैछन् नयाँ काम?
त्रिभुवन विश्वविद्यालयले आफ्नो प्रशासनिक, शैक्षिक तथा प्राज्ञिक संरचनालाई समयानुकूल बनाउँदै डिजिटल सेवा विस्तार, अनुसन्धान प्रवर्द्धन, संस्थागत पुनःसंरचना र वित्तीय सुधारका नयाँ योजना अघि सारेको छ। त्रिविका सहकुलपति एवं शिक्षा तथा खेलकुदमन्त्री सस्मित पोखरेलको अध्यक्षतामा बसेको विश्वविद्यालय सभामा चालु आर्थिक वर्षको नीति तथा कार्यक्रम प्रस्तुत गरिएको थियो। यी योजना कार्यान्वयन भएमा विश्वविद्यालयको प्रशासनिक, शैक्षिक र प्राज्ञिक स्वरूपमा ठूलो फेरबदल आउने अपेक्षा गरिएको ...

इन्टरनेट प्याकेज र शुल्कमा प्राधिकरणको निगरानी, १४ सेवा प्रदायक कारबाहीमा
काठमाडौं । नेपाल दूरसञ्चार प्राधिकरणले स्वीकृत मापदण्ड र निर्देशनविपरीत इन्टरनेट सेवा सञ्चालन गरेको भन्दै १४ वटा इन्टरनेट सेवा प्रदायक कम्पनीलाई जनही ५० हजार रुपैयाँ जरिवाना गरेको छ ।प्राधिकरणले मंगलबार जारी गरेको प्रेस विज्ञप्तिअनुसार अनुमतिपत्रका सर्त उल्लङ्घन गरेको निरीक्षण तथा जाँचबुझबाट पुष्टि भएपछि दूरसञ्चार ऐन, २०५३ को दफा ४७ (१) बमोजिम कारबाही गरिएको हो ।प्राधिकरणका प्रवक्ता मिनप्रसाद अर्यालका अनुसार स्वीकृत प्याकेजअनुसार ...
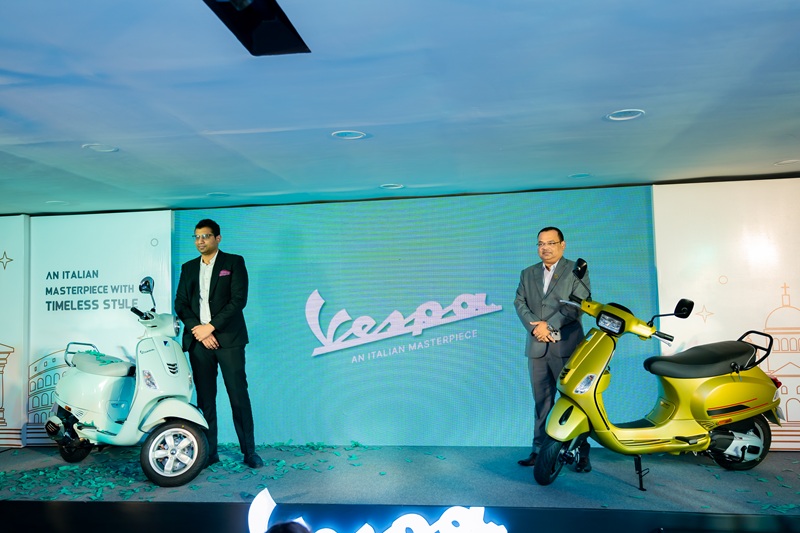
नेपालमा सार्वजनिक भयो भेस्पा १५० एफआई ओबीडी २ स्टेज बी: विशेषता तथा विवरण
२७ असोज, काठमाडौं। इटालियन स्कुटर ब्रान्ड भेस्पाले नेपाली बजारमा नयाँ १५० सिसी क्षमताको स्कुटर सार्वजनिक गरेको छ । नेपालका लागि भेस्पाको आधिकारिक वितरक डेल्टा अटोकर्प प्रालिले भेस्पा १५० एफआई ओबीडी २ स्टेज बी (Vespa 150 FI OBD 2 Stage B) सार्वजनिक गरेको हो । काठमाडौँको त्रिपुरेश्वरस्थित डेल्टा अटोकर्पको शोरुममा आयोजित विशेष कार्यक्रममार्फत नयाँ मोडल सार्वजनिक गरिएको […] The post नेपालमा सार्वजनिक ...
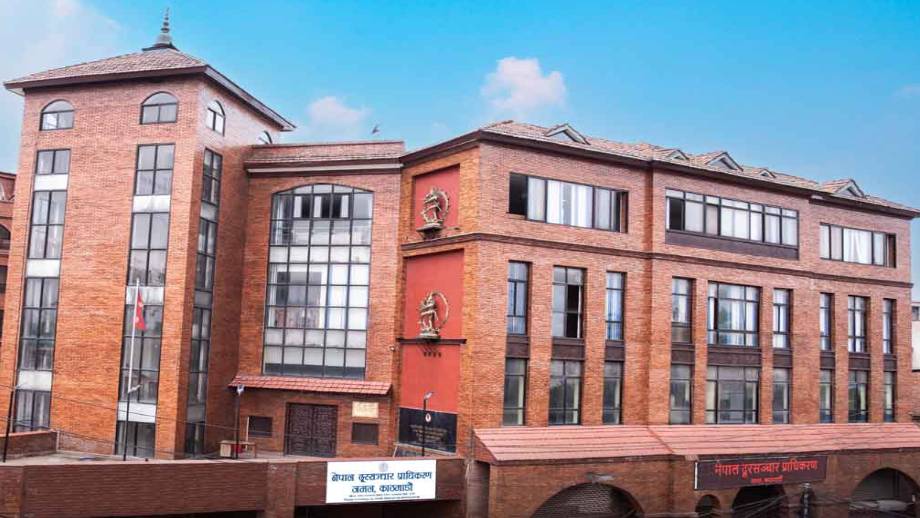
आफूखुशी शुल्क बढाउने १४ इन्टरनेट सेवा प्रदायकलाई प्राधिकरणले तिरायो जरिवाना, स्वीकृति नलिई लागू गरिएका प्याकेज र शुल्क तत्काल बन्द गर्न निर्देशन
नेपाल दूरसञ्चार प्राधिकरणले अनुमतिपत्रका शर्तविपरीत काम गरेको भन्दै १४ वटा इन्टरनेट सेवा प्रदायकलाई जनही ५० हजार रुपैयाँ जरिवाना गरेको छ। प्राधिकरणले आज एक विज्ञप्ति जारी गर्दै इन्टरनेट (इमेलसहित) सेवा सञ्चालन गर्न अनुमति पाएका सेवा प्रदायकले अनुमतिपत्रका सर्त तथा प्रचलित कानुनअनुसार सेवा सञ्चालन नगरेको निरीक्षण तथा जाँचबुझ प्रतिवेदनका आधारमा जरिवाना गर्ने निर्णय गरिएको जनाएको छ। दूरसञ्चार ऐन, २०५३ को दफा ४७(१) बमोजिम ती ...
All Information In One Place
Real-time headlines from trusted sources. Get the app now — stay updated, inspired, and ahead with breaking news!